
Windsor + Northern Colorado | Agent Resource Desk
Clear Roof Answers for Farmers Agents
When a roof question puts a policy conversation, a home purchase or a household budget under pressure, you need construction facts and a practical next step. Drennen helps homeowners evaluate maintenance, repair, restoration and replacement so you can keep the insurance conversation grounded in the roof's actual condition.
Drennen is listed as a preferred provider in the Windsor district's local resource guide. We are an independent contractor, not a Farmers-certified subcontractor. This Drennen resource does not determine insurance coverage or underwriting acceptance.
Northern Colorado since 1973 · Roof systems and related construction · Written scopes and condition photographs
Be the Agent With a Useful Next Step
You do not need to become a roofer. You need a roofer who explains the condition, documents the options and respects the relationship you have with your client.
Protect client trust
Give the homeowner a clear explanation of what is observed, what is uncertain and what can happen next. A roof concern should lead to a reasoned plan, not an automatic replacement pitch.
Request the right document
Tell us whether the need is a condition report, a repair estimate, replacement planning or a limited certification. Agree on the document, scope and fee before the visit.
Keep the roles clear
Drennen addresses construction condition and scope. Your agency and the insurer handle policy interpretation, reporting requirements, coverage and underwriting decisions.
What Does Your Client Need Today?
Clarify Farmers’ Request
- Action
- Confirm what Farmers requires, including the documentation, any required form and the deadline, before ordering an inspection or roofing work.
- Ask Drennen for
- An assessment tailored to that request, with photographs, observed conditions, repair options and limitations within the agreed scope.
- Confirm with the agency
- What documents the carrier will accept and whether repairs or a certification can satisfy the request. Do not assume a roof assessment changes an age-based requirement.
A leak or a concerning roof detail
- Action
- Explain where and when the symptom appeared. Keep people away from a sagging ceiling or water near electrical equipment; use qualified help for hazardous conditions.
- Ask Drennen for
- An investigation of the likely water path, vulnerable penetrations and related details, plus a defined repair or restoration scope where appropriate. Access and concealed conditions can limit the initial findings.
- Confirm with the agency
- Any relevant policy reporting requirements. A contractor's maintenance recommendation is not a coverage decision.
Possible storm damage
- Action
- Record when the condition was noticed, preserve available photos and receipts, and follow the insurer's reporting instructions promptly. Do not postpone a required notice while waiting for an estimate.
- Ask Drennen for
- Photographs and a factual construction assessment of visible damage and repairability. A photo alone may not establish the cause or date of damage.
- Confirm with the agency
- The claim process, applicable policy terms and any inspection/documentation instructions. We do not promise approval or act as the public adjuster.
Planning before the next urgent call
- Action
- Encourage a roof-condition review and maintenance planning before an immediate deadline.
- Ask Drennen for
- Prioritized maintenance, repair/restoration options where viable, or replacement planning when condition warrants it.
- Confirm with the agency
- Accurate roof records and any policy-specific questions about improvements. Neither maintenance nor replacement automatically guarantees a discount or renewal.
Repair, Restore or Replace: Start With the Roof
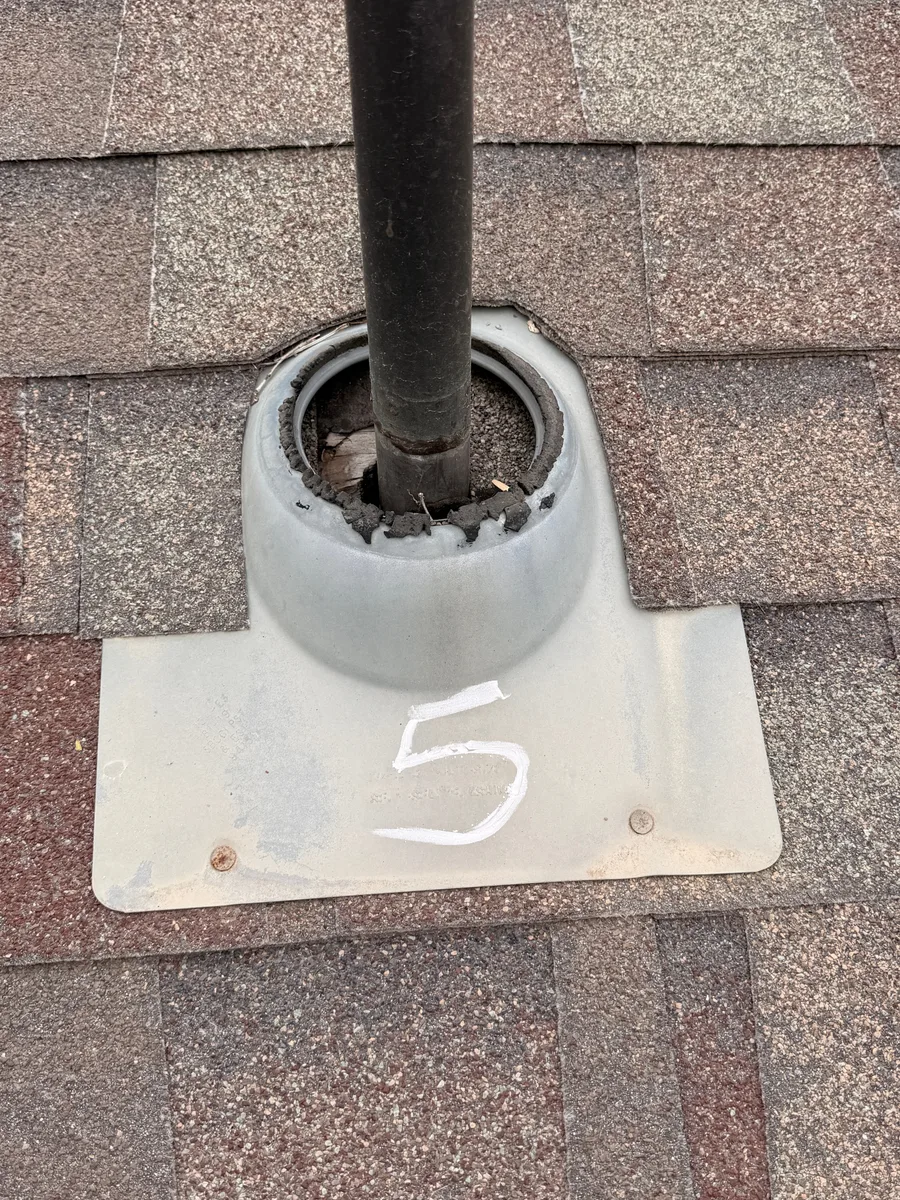
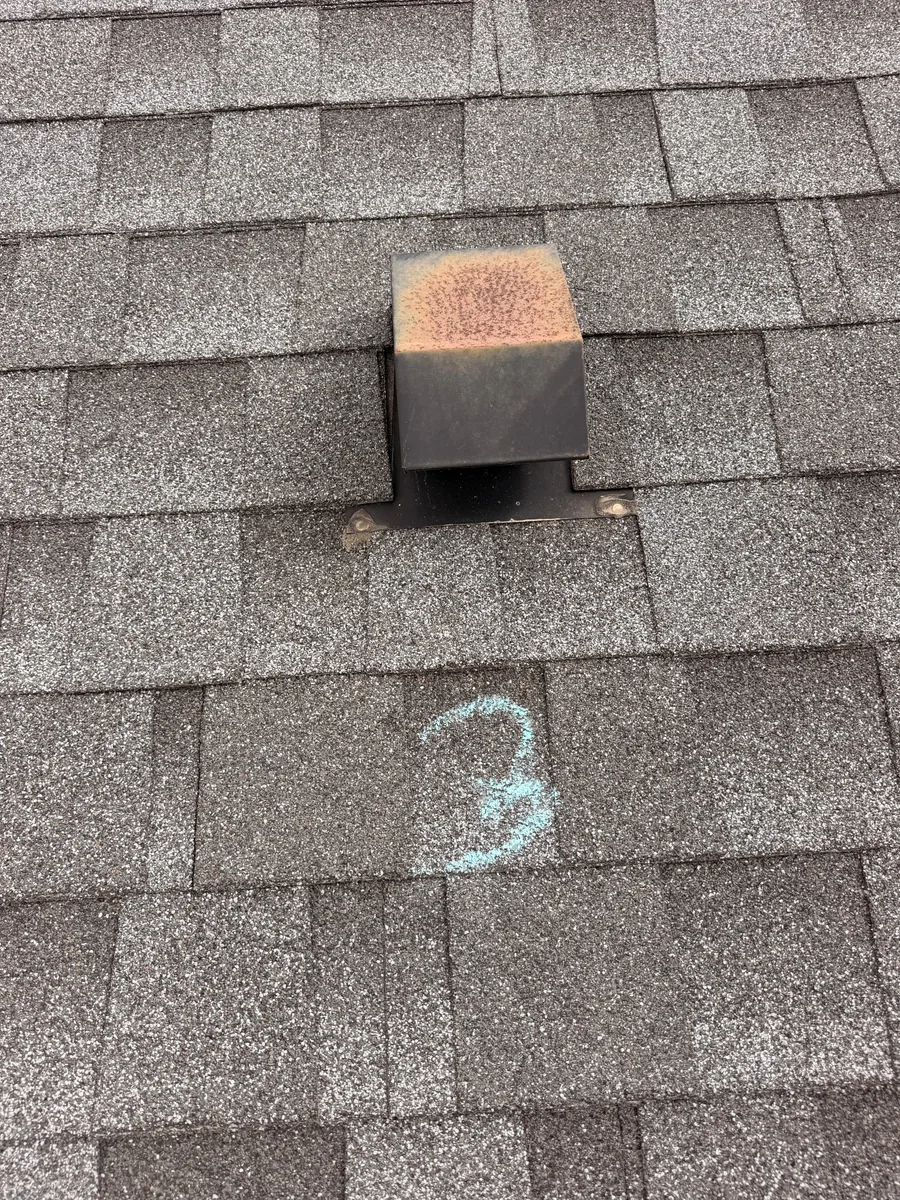
A roof is a system. Pipe boots, vent caps, flashing, fasteners and roof-to-wall details can need attention while surrounding shingles remain serviceable. Drennen's restoration approach means evaluating and coordinating the component work a particular roof needs. It is not a blanket coating, a shingle-rejuvenation treatment or a way to make an unserviceable roof qualify for insurance.
Targeted repair
A defined issue in a limited area; the surrounding system must support a durable repair.
Coordinated restoration
Several correctable details on an otherwise serviceable roof; compare the combined scope, remaining limitations and ongoing maintenance with replacement.
Replacement
Widespread deterioration, poor repairability or a scope that makes continued patching a poor construction or financial choice. We will explain when restoration is not the appropriate path.
A restored roof is not a newly installed roof. Keep the original installation date and the later repair/restoration records distinct. Ask the carrier how it will evaluate the actual work; do not represent restoration as a roof-age reset.
Examples from separate inspections, not Farmers claim files or proof of a particular repair outcome.
Help Clients Compare the Whole Financial Plan
A suitable restoration may preserve cash today. Replacement may be the better choice when deterioration, repair limitations or the total planned work make further investment in the old roof difficult to justify. Compare the written scope, current outlay, maintenance needs, future replacement and the risk of deferring necessary work.
Illustration only: If a roof-specific assessment supports a $2,500 restoration instead of an immediate $25,000 replacement, the difference in today's outlay is $22,500. This is an illustration, not a quoted package, an insurance benefit or a guaranteed life extension. Future maintenance and replacement still need to be planned.
Compare roof replacement costs and scopes
A Covered Roof Loss Can Still Leave a Budget Gap
A claim does not have to be denied for the homeowner to face a substantial expense. A wind or hail deductible, depreciation or a roof-payment schedule can leave a gap between the insurance payment and the construction cost. Your agency explains the policy; Drennen helps the homeowner plan the work around their actual budget.
Percentage deductibles: use the dwelling limit
Many Colorado policies have a separate wind or hail deductible. When it is percentage-based, the calculation commonly uses the insured dwelling amount shown in the policy, not the roof estimate or the home’s sale price. For example, 2% of $600,000 is $12,000. Separate losses can each involve a deductible; ask how the specific policy applies rather than assuming earlier deductibles accumulate toward the next storm.
ACV and RCV: know what can be recovered
Actual cash value (ACV) accounts for depreciation. Replacement cost value (RCV) generally covers eligible repair or replacement without a final deduction for depreciation, subject to the policy. An RCV claim may start with a depreciated payment, with eligible depreciation recoverable after required work and documentation. A small initial check is not proof of ACV-only coverage. Ask whether the roof has ACV-only terms, recoverable depreciation or a separate payment schedule.
| Item | RCV coverage | ACV-only coverage |
|---|---|---|
| Wind/hail deductible (2% of $600,000) | $12,000 | $12,000 |
| Assumed depreciation | $10,000, recoverable if conditions are met | $10,000, not recoverable |
| Illustrative total insurer payment | $13,000 after eligible depreciation is recovered | $3,000 |
| Homeowner portion of the $25,000 cost | $12,000 | $22,000 |
Fictional numbers, not a Farmers quote or claim determination. Assumes the full $25,000 scope is covered, the stated deductible and depreciation apply, and all RCV recovery conditions are met. Actual limits, endorsements, incurred costs and settlement terms control. No deductible is waived.
Understand the pressure. Offer a workable plan.
Colorado’s Division of Insurance identified hail as a major homeowners-insurance cost driver in its February 2026 study. Higher deductibles and different settlement terms can shift more of a roof expense to the homeowner. A policy can still provide important protection while leaving repairs, depreciation or the deductible to be budgeted separately.
Drennen supports the agent with clearly scoped estimates homeowners can compare, targeted repair or restoration when the roof is suitable, realistic replacement planning and available financing subject to approval and lender terms. The goal is a manageable construction plan that respects the policy and the homeowner’s finances, rather than relying on the next storm to fund a roof.
Help your client understand their roof coverage
Confirm your client’s wind/hail deductible in dollars, how the policy values roof damage, whether depreciation is recoverable, any roof-payment schedule, and reporting or completion deadlines. Help them understand those requirements while Drennen explains the construction options. Remind them not to delay required reporting or necessary steps to prevent further damage.
When a Claim Is Denied, Help Keep the Relationship Strong
A denied claim can leave a homeowner worried about the cost of their roof and frustrated with the person they trusted for help. A practical next step can change that conversation. Drennen helps you move from a difficult coverage discussion to a clear plan for the home, the budget and what comes next.
Help the client understand the decision
When a roof condition falls outside the policy’s coverage, you and the Farmers claims team can explain the decision and the applicable policy terms. Drennen can explain the roof’s physical condition and construction options in plain language. We keep those roles clear, so the homeowner can understand why a roof may need attention even when insurance does not pay for the work.
Look for a manageable alternative to immediate replacement
If the roof remains serviceable, targeted repairs or a coordinated restoration may address vulnerable penetrations, flashing and other repairable components at a lower immediate cost than full replacement. We explain what the proposed work addresses, what it leaves in place and when replacement is the more responsible choice.
Turn remaining roof life into planning time
After assessing the roof, Drennen can discuss a condition-based planning range for continued service, where supportable, along with maintenance needs and signs that would change the recommendation. For a suitable roof, restoration may give the homeowner time to build a replacement fund instead of facing the entire expense at once. Any projected additional years are specific to that roof, not a blanket promise or a guarantee against future storm damage.
Make the payment conversation part of the plan
Ask Drennen about available financing options and current terms. Financing is subject to approval and the applicable lender’s terms. We help the homeowner compare the work scope and overall cost with their budget, without promising a particular rate, payment or approval.
Your client should leave the conversation knowing that a coverage denial does not mean they have run out of options. Our goal is to help reduce uncertainty, protect the home and put a manageable plan in place, so they can get back to their life and continue to see their agent as a resource.
Coverage decisions and any questions about review remain with Farmers. Drennen does not determine whether a denial is correct, and a repair or restoration does not guarantee renewal, coverage or a particular roof lifespan.
Ask for a Useful Roof Documentation Package
The assignment determines what Drennen can provide. Ask our office to confirm these items, the fee and any access requirements before scheduling:
- Purpose, inspection date, accessible areas and assessment limitations.
- Labeled condition photographs and the location of relevant observations.
- Observed conditions separated from owner-reported history and unverified causes.
- A prioritized scope: immediate concerns, repair/restoration options, maintenance or replacement planning.
- A written estimate identifying included work, exclusions and what could change after concealed conditions are opened.
- If work is completed, the agreed completion records, photographs, invoice and applicable written warranty information.
- If a certification is requested and the roof qualifies, its separate written term, conditions and exclusions.
- Current contractor credential and insurance information appropriate to the requested work, available for verification.
A roof inspection, a condition report and a limited roof certification are different services. Confirm the carrier's requirements before paying for a document. None guarantees insurability, coverage, premium savings or acceptance by a particular carrier.
Your Agent Referral Checklist
Have the homeowner's permission before sharing their information. For the initial request, use the contact form or call our office. Do not put private client details into a public comment or analytics link.
- Agency and agent contact:
- Homeowner permission to coordinate:
- Homeowner contact and property location:
- Reason for the assessment: condition / renewal request / leak / possible storm damage / planning
- Exact receiving-party requirement or form, if any:
- Due date and known scheduling constraints:
- Known installation date, prior repairs and available records:
- Observed symptoms and when they were first noticed:
- Requested deliverable: condition report / repair estimate / replacement estimate / certification inquiry
- Who should receive the agreed findings, with homeowner permission:
- Confirm scope, fee and availability before scheduling.
Policy numbers, claim numbers and full policy documents are not needed in the initial website request. The office can arrange any appropriate follow-up privately.
In the message, write "Farmers agent referral" and your agency name so the office understands the context.
Optional homeowner introduction (selectable):
"Drennen can assess the roof's condition and explain repair, restoration or replacement options. I can help with your policy questions. The contractor's findings do not determine coverage or guarantee that the insurer will accept the roof."
Questions Agents Ask
Keep the Relationship. Bring Us the Roof Question.
Start with the client's concern and the document you need. We will help define the construction assignment so your agency can keep doing what it does best: guiding the client through the insurance conversation.
Based in Fort Collins, serving Windsor, Loveland, Timnath, Longmont, Greeley and surrounding Northern Colorado communities. The office confirms availability for the property and scope.
Sources for the Conversation
- Farmers: Roof leaks and insurance considerations
- Farmers: Factors affecting homeowners insurance cost
- Farmers: Home maintenance checklist
- ARMA: Asphalt shingle repairability
- Farmers: Hail coverage and deductible questions
- Colorado DOI: Hail deductibles and claim questions
- NAIC: Roof replacement cost versus actual cash value
Last reviewed October 2026. General construction information. Actual policy terms and insurer instructions govern insurance decisions.